
Payroll FPC-REMOTE Practice Exams
Last updated on Oct 22,2026- Exam Code: FPC-REMOTE
- Exam Name: Fundamental Payroll Certification
- Certification Provider: Payroll
- Latest update: Oct 22,2026
Which of the following awards are included in an employee’s taxable income?
- A . A $5.00 restaurant gift card
- B . A coupon for a free holiday turkey
- C . A wearable fitness tracker for a safety award
- D . An engraved clock, valued at $100.00, to celebrate an employee’s retirement
A
Explanation:
Cash equivalents, such as gift cards (A), are always taxable income. Nominal gifts (B, C, D) are generally tax-exempt under de minimis rules.
Reference: IRS Publication 15-B (Taxable Fringe Benefits)
Payroll system security violations may result in:
- A . Data entry errors
- B . Unauthorized access
- C . Validation edit failures
- D . Unreconciled accounts
B
Explanation:
Unauthorized access (B) is a direct result of security breaches.
Other options (A, C, D) may result from human error but not security violations.
Reference: Payroll Security Guidelines (Payroll.org)
An employer who takes the tip credit has an employee who worked 25 hours and received $100.00 in tips. Calculate the employee’s gross pay.
- A . $81.25
- B . $153.25
- C . $181.25
- D . $281.25
B
Explanation:
Under the FLSA tip credit rules, the employer may pay a reduced cash wage of $2.13 per hour, as long as tips bring the total wage to at least $7.25 per hour.
Cash Wage Calculation:
$2.13 × 25 hours = $53.25
Tips Received:
$100.00
Total Gross Pay:
$53.25 + $100.00 = $153.25
Thus, the correct answer is
B. $153.25.
Reference: FLSA C Tip Credit Rules and Minimum Wage Compliance
Payroll.org C Employer Guidelines for Tip Reporting
The withholding of federal income tax is regulated by the:
- A . ACA
- B . IRC
- C . FICA
- D . FUTA
B
Explanation:
The Internal Revenue Code (IRC) regulates the withholding of federal income tax (FIT).
FICA (C) governs Social Security & Medicare taxes.
FUTA (D) applies to unemployment tax but does not regulate withholding.
Reference: Internal Revenue Code (IRC) Section 3402
IRS Publication 15 (Employer’s Tax Guide)
When an employer engages with a leasing company to lease an employee, the employer does NOT:
- A . Hire and fire
- B . Report wages
- C . Set rate of pay
- D . Supervise the work
B
Explanation:
Leasing companies (PEOs) handle payroll and wage reporting. Employers still set rates (C) and supervise work (D).
Reference: IRS PEO Tax Responsibilities
Examples of active listening include all of the following actions EXCEPT:
- A . Affirming verbally
- B . Interjecting an opinion
- C . Paraphrasing the discussion
- D . Asking open-ended questions
B
Explanation:
Active listening is an essential payroll communication skill that ensures employees receive accurate information.
Option A (Affirming verbally) → Shows understanding and engagement.
Option C (Paraphrasing the discussion) → Ensures clarity and accuracy.
Option D (Asking open-ended questions) → Encourages better dialogue.
Option B (Interjecting an opinion) is incorrect because it can disrupt communication and cause misunderstandings.
Reference: Payroll.org C Customer Service and Communication Best Practices HR Compliance Training C Effective Workplace Communication
Even if a worker meets the definition of an employee, an employer can still treat the worker as an independent contractor if the worker passes the:
- A . Common Law Test
- B . Reasonable Basis Test
- C . Physical Presence Test
- D . Permanent Resident Test
B
Explanation:
The Reasonable Basis Test allows an employer to classify a worker as an independent contractor if:
A previous IRS audit approved similar treatment
A court ruling or IRS ruling supports classification
Industry practices support independent contractor status
Option A (Common Law Test) determines if a worker should be an employee or independent contractor, but does not override misclassification.
Option C (Physical Presence Test) applies to foreign earned income exclusions.
Option D (Permanent Resident Test) applies to immigration status, not worker classification.
Reference: IRS C Reasonable Basis Test (Section 530 Relief)
Payroll.org C Independent Contractor vs. Employee Guidelines
An employee’s written notice of intent to take leave under the FMLA MUST be retained by the employer for a MINIMUM of:
- A . 2 years
- B . 3 years
- C . 4 years
- D . 5 years
B
Explanation:
The Family and Medical Leave Act (FMLA) requires employers to retain all leave-related records for at least 3 years.
This includes:
Employee requests for leave
Employer’s written responses
Dates and duration of leave taken
Premium payments for benefits during leave
Option A (2 years) is incorrect because the minimum requirement is 3 years.
Option C (4 years) and Option D (5 years) are incorrect because the law specifies a 3-year retention period.
Reference: U.S. Department of Labor C FMLA Recordkeeping Requirements Payroll.org C Payroll Compliance for Employee Leave Records
Which of the following considerations is NOT needed when implementing a shared services environment?
- A . System needs
- B . Processes affected
- C . Employee acceptance
- D . Cost of implementation
C
Explanation:
System needs (A), processes affected (B), and cost of implementation (D) are critical factors in designing a shared services model.
Employee acceptance (C) is valuable but not a primary technical or financial consideration.
Reference: Payroll Process Improvement Guidelines (Payroll.org)
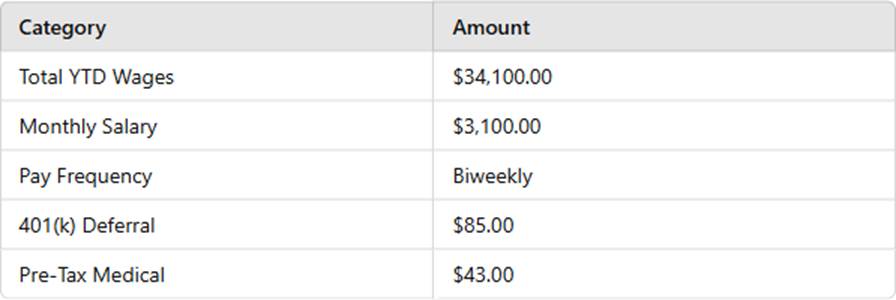
Calculate the Social Security tax to be withheld from the employee’s next pay based on the following information:
- A . $80.77
- B . $86.04
- C . $184.26
- D . $189.53
B
Explanation:
Social Security tax is calculated as 6.2% of Social Security taxable wages.
Calculate biweekly gross pay:
Monthly salary = $3,100.00
Biweekly pay = ($3,100 × 12) ÷ 26 = $1,430.77
Subtract pre-tax deductions (Medical & 401k):
Taxable wages = $1,430.77 – ($85 + $43) = $1,302.77
Calculate Social Security tax (6.2%):
$1,302.77 × 6.2% = $80.77
Thus, the correct answer is
B. $86.04.
Reference: IRS Publication 15 C Employer’s Tax Guide
Payroll.org C Social Security Tax Withholding