
Payroll FPC-REMOTE Practice Exams
Last updated on Oct 21,2026- Exam Code: FPC-REMOTE
- Exam Name: Fundamental Payroll Certification
- Certification Provider: Payroll
- Latest update: Oct 21,2026
What is the purpose of Form I-9?
- A . To request an ITIN
- B . To determine how much FIT to withhold from a paycheck
- C . To summarize taxable wages earned during the calendar year
- D . To verify the identity and employment authorization of a worker
D
Explanation:
Form I-9, Employment Eligibility Verification, is used by employers to:
Verify the identity of newly hired employees
Ensure employees are legally authorized to work in the U.S.
Prevent illegal employment practices
Option A (Request an ITIN) is incorrect because an ITIN (Individual Taxpayer Identification Number) is requested using Form W-7, not I-9.
Option B (Determine FIT withholding) is incorrect because Form W-4 is used for federal income tax withholding, not Form I-9.
Option C (Summarize taxable wages) is incorrect because Form W-2 summarizes taxable wages.
Reference: U.S. Citizenship and Immigration Services (USCIS) C Form I-9 Instructions Payroll.org C Employment Eligibility Verification Guide
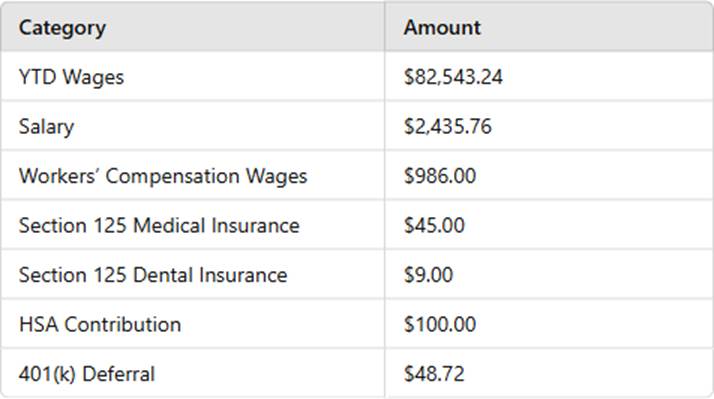
Using the following information, calculate the social security tax to be withheld.
- A . $138.45
- B . $141.47
- C . $160.58
- D . $202.60
B
Explanation:
Social Security tax is calculated at 6.2% of Social Security taxable wages.
Determine taxable wages:
Gross salary = $2,435.76
Subtract pre-tax deductions (Section 125 and HSA):
Medical: $45.00
Dental: $9.00
HSA: $100.00
Taxable wages = $2,435.76 – ($45 + $9 + $100) = $2,281.76
Social Security tax = $2,281.76 × 6.2% = $141.47
Reference: IRS C Social Security and Medicare Tax Guide (Publication 15)
Payroll.org C Social Security Tax Calculation Rules
To ensure net pay is correct and taxes are deposited timely, which items need to be reconciled?
- A . General ledger accounts and payroll register only
- B . Accounts payable payments and end-of-the-month balances only
- C . Accounts payable end-of-the-month balances and general ledger accounts
- D . Accounts payable payments and end-of-the-month balances; general ledger entries and payroll register
D
Explanation:
Payroll reconciliation ensures that payroll transactions match financial records to avoid errors in tax deposits, employee payments, and financial reporting.
The correct answer includes all necessary reconciliation points:
Accounts payable payments (ensure wages were paid)
End-of-the-month balances (cross-check payroll liabilities)
General ledger entries (confirm correct postings)
Payroll register (check against wage statements)
Option A is incorrect because payroll must also be reconciled with accounts payable and monthly balances.
Option B & C are incorrect because they exclude payroll register validation.
Reference: Payroll.org C Payroll Reconciliation Best Practices
IRS C Employer’s Tax Guide (Publication 15)
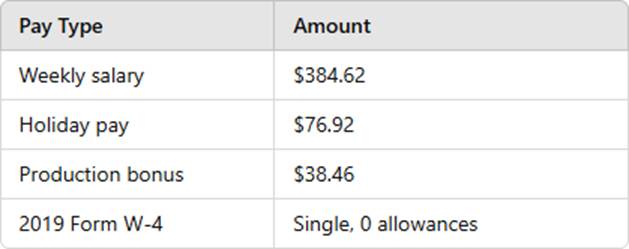
Using the percentage method for automated payroll systems, calculate the federal income tax withholding based on the following information:
- A . $18.65
- B . $26.92
- C . $39.04
- D . $41.69
C
Explanation:
Total taxable wages: $384.62 + $76.92 + $38.46 = $500.00 Using IRS percentage method tables, withholding = $39.04
Reference: IRS Publication 15-T (Tax Withholding Tables)
When testing a payroll business continuity plan, all of the following tasks are critical to issuing payments to employees EXCEPT:
- A . Validating system access.
- B . Adding a new cost center.
- C . Creating the ACH file.
- D . Printing paychecks.
B
Explanation:
A payroll business continuity plan (BCP) is designed to ensure payroll processes continue during a disruption. Critical tasks include validating system access, creating ACH files, and printing paychecks. Adding a new cost center is NOT critical to issuing payroll, as it primarily affects financial reporting rather than payment processing. Payroll.org recommends focusing on system access, banking functions, and ensuring payroll runs smoothly.
Reference: Payroll.org, Business Continuity and Disaster Recovery Guidelines IRS Publication 15 (Employer’s Tax Guide)
A willful violation of child labor laws, that does NOT involve serious harm or death, can result in a fine of up to:
- A . $1,000.00
- B . $2,203.00
- C . $10,000.00
- D . $13,227.00
D
Explanation:
The Fair Labor Standards Act (FLSA) establishes child labor laws, and violations can result in fines.
As of recent updates, the penalty for a willful violation of child labor laws is $13,227.00 (adjusted annually).
If serious injury or death occurs, penalties increase significantly.
Reference: FLSA Child Labor Penalty Guidelines (DOL)
Wage and Hour Division (DOL)
All of the following statements about the implementation of department processes are true EXCEPT:
- A . Each team member has a clear and concise assignment.
- B . A backup manager is identified and participating in the project.
- C . The standards for measuring success must be clear and specific.
- D . Managers who delegate properly have less time to focus on work.
D
Explanation:
Managers who delegate properly actually have MORE time to focus on work, not less. Delegation improves efficiency and productivity by allowing managers to focus on strategic tasks.
Options A, B, and C are correct as they are key to successful implementation of processes.
Reference: Payroll Process Best Practices (Payroll.org)
Employee privacy rights are NOT governed by:
- A . Company policy
- B . Federal law
- C . FLSA
- D . State regulations
C
Explanation:
FLSA governs wages and hours, not privacy rights.
Privacy laws are governed by federal/state regulations and company policies.
Reference: Employee Privacy Rights (DOL)
To reconcile a general ledger tax liability account balance, verify all of the following items EXCEPT:
- A . Entries from company accountants
- B . Checks issued by accounts payable
- C . Account entries against the payroll register
- D . Account activity against the quarterly returns
A
Explanation:
To properly reconcile payroll tax liability accounts, the following steps are performed:
Compare account entries against payroll registers (C) C Ensures wages, deductions, and taxes are posted correctly.
Verify checks issued by accounts payable (B) C Confirms tax payments were made.
Match account activity with quarterly tax returns (D) C Ensures payroll taxes were reported correctly on Form 941.
Option A (Entries from company accountants) is incorrect because accountants do not create payroll entries; payroll is recorded based on actual payroll transactions, not estimates or adjustments from accountants.
Reference: GAAP Accounting Standards C Payroll Tax Liability Reconciliation
Payroll.org C Best Practices for Payroll Tax Account Reconciliation